

Four | Buy Now, Pay Later
by Four Technologies, Inc
4.4
- Safety
- 100% Safe
- Category
- Shopping
- Ratings
- 4.4
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
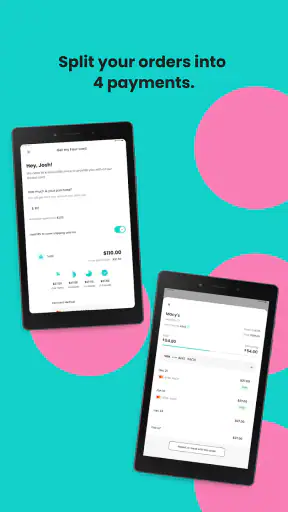
 Analysis by Getfullapps
I came away from Four with a fairly clear impression: its value depends less on discovering products and more on how comfortably you can divide a purchase into scheduled payments. That single capability shapes almost every part of the experience. If you already know what you want and need a little breathing room in your budget, the app can feel focused and convenient. If you are looking for deep shopping tools, broad financial planning, or a way to make expensive purchases harmless, it is a much less convincing choice.
Four is a free shopping app from Four Technologies, Inc. It is available for Everyone and works on devices running Android 6.0 or later. The app has reached over a million installs, with an average rating of 4.4 from around thirteen thousand ratings and about five thousand reviews. Those figures suggest that the basic idea works for a substantial group of shoppers, although they do not remove the need to look carefully at each purchase before committing.
Splitting a purchase is the experience, not just an extra feature
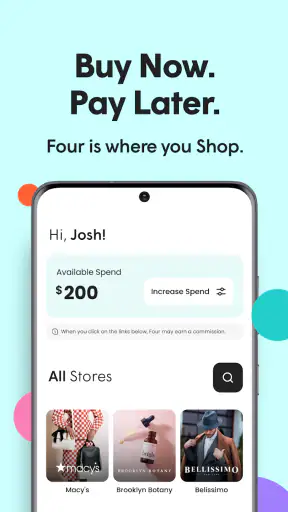
The central appeal is straightforward: Four lets me shop now and arrange payment over time instead of paying the entire amount at once. In practice, that changes the moment when I decide whether something fits my budget. Rather than asking only, “Can I pay for this today?”, I have to ask, “Can I reliably handle each scheduled payment after today?” That is a useful distinction, and it is also where the app requires the most discipline.
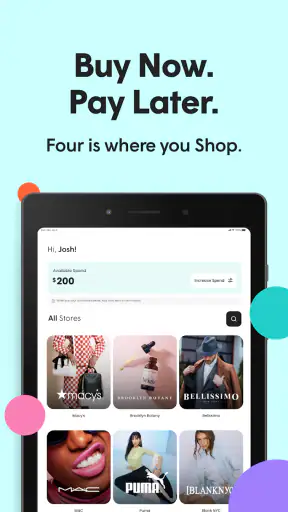
I would not describe this as a normal marketplace that happens to offer financing. The important action is choosing a purchase and using the app’s payment approach at checkout. The shopping side is therefore most useful when I already have a specific item or retailer in mind. It is less compelling if I want editorial recommendations, detailed product comparisons, or a broad catalog organized around hobbies and interests.
The app’s store summary presents it as a way to shop online and pay later with flexible payments. I found that description most accurate when thinking of Four as a checkout companion. It can make a planned purchase easier to manage, but it does not change the underlying cost of the item or make an unnecessary purchase sensible. The flexibility is a timing tool, not extra income.
That distinction matters because payment apps can encourage people to focus on the first amount due. My advice is to treat the full purchase as already spent and the later payments as obligations that need room in the household budget. I would open Four only after checking the ordinary price, delivery terms, and return conditions of the item. A convenient payment schedule should never replace those checks.
What using Four feels like during a normal purchase
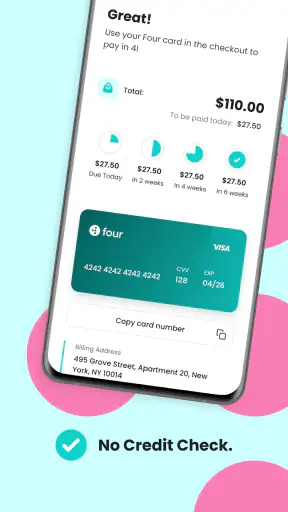
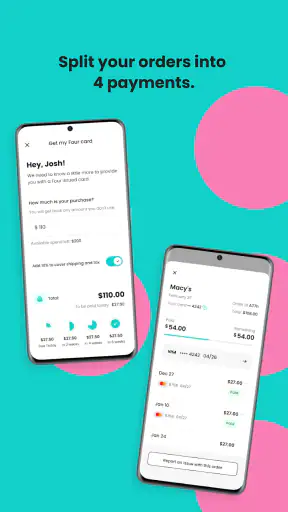
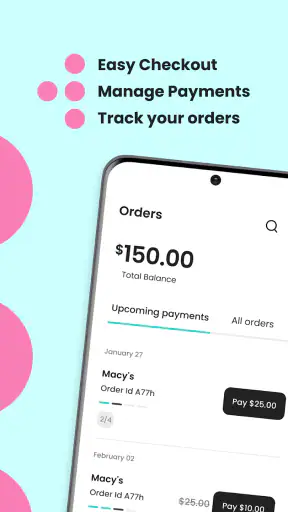
My practical workflow would be simple. I would decide what I need, check the total, open Four at the point where the payment option is available, and review the schedule before confirming. The most important screen is not the product image or the initial installment; it is the complete commitment shown together. That is where I would look for the timing of future payments and make sure the dates do not collide with rent, utilities, subscriptions, or another planned purchase.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
This is one of the less obvious benefits of using a dedicated payment app: it encourages me to pause before tapping the final button. With a regular card, the transaction can feel finished immediately. With Four, the split arrangement makes the future cost more visible. That can be helpful for planned spending, provided I actually read the details instead of treating the first payment as the whole price.
I would also keep the app updated. The current version is 1.17.84, and payment applications are the kind of software where compatibility and checkout behavior matter more than they do in a casual game. Four has been available since January 22, 2021, so it is not a brand-new experiment, but the experience can still depend on the retailer, the device, and the specific transaction.
One practical habit I recommend is taking a moment to record the future payment dates in whatever budgeting system I already use. I would not rely on memory or assume that a notification alone will protect me from overspending. This small step turns Four from an impulse-enabler into a more deliberate budgeting aid. It also exposes a trade-off that is easy to miss: several individually manageable purchases can become difficult when their schedules overlap.
A realistic everyday scenario
Imagine that I need a replacement household item after an unexpected breakdown. Paying the full amount immediately could disrupt the rest of the week’s budget, while postponing the purchase could create an even bigger inconvenience. In that situation, Four may give me a practical middle path: I can address the problem now while spreading the obligation across later payments.
The sensible way to use it would be to compare the total with the ordinary checkout amount, confirm that the item can be returned if necessary, and then check the upcoming dates against my next pay cycle. I would also leave room for delivery problems or a replacement purchase. The app helps with timing, but it cannot make a faulty product, an unsuitable size, or a delayed refund less frustrating.
There is another useful scenario for a planned purchase that I know I can afford but would rather align with my monthly cash flow. For example, I might choose Four for a necessary upgrade after deciding that the full total is acceptable and the later payments fit comfortably. In that case, the service is not rescuing me from an unaffordable purchase; it is helping me organize a purchase I had already budgeted for.
That is the best-case use in my view. The weakest use is buying something mainly because the initial payment looks small. If I would not buy the item at its full price, I should not use a split payment to talk myself into it. Four makes the decision easier to execute, not necessarily wiser.
Where it differs from paying normally
A standard debit card keeps the transaction simple: the money leaves at once, and there are no later payment dates to track. That simplicity is valuable for anyone who prefers finality or tends to forget recurring obligations. A regular credit card may offer more familiar statements, broader account tools, or rewards depending on the card, although it can also make it easy to carry a balance. Four sits between those habits by making installment timing central to the purchase.
Compared with a retailer’s own payment arrangement, Four can be attractive when I want a consistent app-based process rather than a different system at every store. The trade-off is that the retailer’s option may be more naturally integrated into its checkout, while a dedicated service may require me to understand another account and another schedule. I would choose based on clarity, total cost, and how easy it is for me to manage the commitment, not simply on the number of installments shown.
Four is also different from a shopping browser or price-comparison app. Those tools help me find a lower price or evaluate alternatives before checkout. Four becomes most relevant after I have narrowed the decision to a purchase. Using it does not remove the need to compare prices elsewhere, and I would not assume that a payment split represents the best deal available.
The friction I would consider before installing it
The first limitation is behavioral. Dividing a purchase can reduce the psychological impact of the total, which may lead me to buy more often or accept a higher price than I normally would. The app is useful only when I impose my own spending limit. I would keep a running list of active payment commitments and avoid starting a new one simply because the first amount seems comfortable.
The second limitation is that convenience depends on the checkout experience. A payment method can look appealing in an app but still feel less smooth if I have to switch between screens, verify information, or resolve a problem after ordering. I would not make Four my only way to pay until I had completed a small, non-urgent purchase and understood how the process fits my routine.
Returns deserve special attention. A returned item does not necessarily erase the need to understand what happens to a payment schedule, and I would keep order confirmations, return tracking, and any support messages until the transaction is fully settled. This is not a criticism unique to Four; it is a reason to be more organized whenever a purchase is divided over time.
I would also skip it for purchases that I cannot comfortably afford even when spread out. That includes essential expenses competing with bills, items whose value is uncertain, and impulse purchases made late at night or under time pressure. A payment app should not be used as a substitute for an emergency fund or a debt plan.
Another trade-off is mental overhead. One full payment is easy to remember. Several future payments require attention, even when each one is modest. Someone who already has multiple subscriptions, cards, and installment plans may gain less from Four than a shopper with a simple budget and a clear reason for using it.
Small habits that make the service safer to use
I would start by setting a personal rule: only use Four when the complete purchase total is already approved in my budget. The app can then decide the timing, but it does not decide whether the purchase is responsible. This rule prevents the most common mistake, which is judging affordability by the first scheduled amount.
Next, I would review the schedule immediately after checkout and place it beside my other financial reminders. I would not wait for a notification to discover that two payments fall in the same week. This is a simple workflow, but it is more valuable than any extra shopping convenience because it keeps Four connected to the rest of my finances.
For larger or important purchases, I would save the order details and check the retailer’s return window before the first payment is due. That gives me time to act if the product is wrong or the order changes. I would also avoid using the app for several unrelated purchases at once. Keeping one planned transaction visible makes it easier to judge whether the payment experience is genuinely helping.
Finally, I would compare the full checkout amount with other payment methods before accepting the plan. The attractive part of Four is flexibility, but flexibility is not automatically a discount. If another option offers a clearer total or better protection for my particular purchase, I would choose that instead.
Who is likely to benefit most
Four makes the most sense for a shopper who buys online, understands the full cost of what they want, and has predictable income or a reliable budget. That person may appreciate spreading a planned expense without turning every purchase into a long-term financial project. The app is especially practical when cash flow is temporarily tight but the purchase is necessary and the later payments are genuinely manageable.
It can also suit someone who prefers seeing a defined schedule rather than carrying an open-ended card balance. The fixed structure can make the commitment easier to visualize, as long as the user checks every active plan and does not stack too many of them. In my experience, the app’s strongest advantage is this visibility around a single purchase.
I would recommend caution to students, irregular earners, and anyone whose essential expenses already consume most of their income. A flexible payment date does not make income more predictable. I would also point cautious shoppers toward ordinary payment methods if they value simplicity above all else or do not want another account to monitor.
The age rating of Everyone makes Four broadly accessible from a store perspective, but that should not be confused with universal financial suitability. The right question is not whether someone can install it; it is whether the person can manage the complete obligation without sacrificing necessities. That is the standard I would use before recommending it to a friend.
My final view after focusing on the payment experience
Four is a focused shopping app rather than a complete personal-finance solution. Its payment-splitting capability can be genuinely useful when I have a necessary or carefully planned purchase and want to align the cost with my budget. The experience is clearest when I treat the app as a checkout tool and keep the full amount, future dates, and return details in view.
I would recommend trying it for a modest, planned online purchase rather than beginning with something expensive or urgent. That gives me a chance to understand the workflow and decide whether the scheduled payments make my finances clearer or more complicated. If I prefer one-and-done payments, detailed price research, or strict separation from installment commitments, a debit card, credit card, or comparison service may be a better fit.
Overall, I see Four as worthwhile for disciplined shoppers who want controlled flexibility. The best reason to use it is not that the first payment feels small, but that the entire schedule fits a purchase I already know I can afford. Used with that mindset, the app can make online shopping more manageable without pretending that delayed payment removes the cost.
Pros
- Simple checkout process for eligible purchases
- Flexible repayment options can help manage short-term expenses
- Useful for spreading the cost of larger purchases
- Available through participating online and retail merchants
- Payment reminders help users keep track of upcoming installments
Cons
- Late or missed payments may result in fees or account restrictions
- Not all purchases, merchants, or users are eligible
- Frequent use can encourage unnecessary spending
- Approval decisions may vary between transactions
- Returns and refunds can take time to update the payment plan
FAQs for Four | Buy Now, Pay Later
What is Four, and how does its Buy Now, Pay Later service work?
Four is a shopping and payment service that lets eligible customers split a purchase into multiple installments instead of paying the full amount immediately. At checkout, you select Four as the payment method, review the repayment schedule, and complete the order if approved. The exact installment structure, fees, and available options can vary depending on the retailer, purchase amount, account status, and applicable terms.
Does Four charge interest, fees, or a down payment?
Four commonly presents installment plans with a scheduled initial payment followed by additional payments, but the cost can differ by transaction and merchant. Some plans may be interest-free, while other circumstances could involve fees, late-payment charges, or different terms. Before confirming an order, carefully check the total repayment amount, due dates, and any applicable charges shown in the app or at checkout.
What eligibility and information are required to use Four?
To use Four, you generally need to meet the service’s age, location, account, and payment requirements. The app or checkout process may request personal details, contact information, and a valid debit or credit card. Four may also perform an eligibility or approval assessment for each purchase, so having an account does not guarantee that every transaction will be accepted.
Can I use Four for every online or in-store purchase?
No. Four is available only with participating merchants and for products or transactions that meet the company’s conditions. Certain categories, order values, subscriptions, gift cards, or restricted items may not qualify. Availability can also depend on your country, the retailer’s checkout system, and whether the purchase is made online or in person. Always look for Four among the payment options before relying on it.
What happens if I miss a Four installment or need a refund?
If an installment is missed, Four may retry the payment, restrict future purchases, or apply a late fee according to the agreement for your plan. A refund usually begins with the retailer, and the way it affects remaining installments can depend on the merchant’s refund process and Four’s policies. Contact the retailer and Four support promptly, and review your payment schedule rather than assuming payments stop automatically.

Four | Buy Now, Pay Later
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@paywithfour.com, visit https://paywithfour.com/, or review their https://paywithfour.com/legal/privacy-policy.










